
Source : THE AGE NEWS
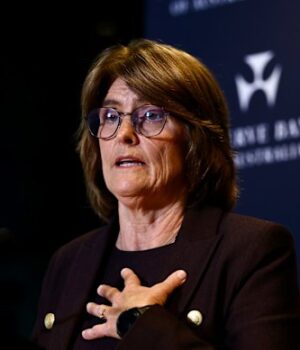
When Reserve Bank governor Michele Bullock said last month that unemployment would “probably need to rise” to between 4.5 per cent and 5 per cent, she ruffled a few feathers, but she wasn’t wrong. With all that’s going on in the world, higher unemployment is probably a price we need to pay to stop inflation, or price growth, spiralling out of control.
That doesn’t mean the bank should get comfortable with an unemployment rate that sits above 4.5 per cent. That might, by historical standards, seem like an acceptable share of people unable to find work. But it’s not where we should aim to be.
What we need is for unemployment to sit at a level where businesses aren’t fighting tooth and nail for workers — because when they do, a battle to attract workers using higher wages can feed into higher prices as firms look to recoup their costs.
It’s a good thing to have as many people (who want work) matched up to jobs as possible because it can give them greater financial stability, a sense of purpose or belonging and fulfillment.
The problem is not that Bullock thinks unemployment should sit a bit higher. It’s that the bank seems convinced unemployment should probably stay higher than it has been for the past few years, even once many of the external shocks (such as the Middle East conflict) have passed.
Right now, Bullock may seem a villain to some. She has pulled interest rates up to a 15-year-high, leaving plenty of mortgage payers gritting their teeth as more of their income disappears into interest payments. As if that wasn’t enough, Bullock says the unemployment rate, which has steadily climbed over the past few years, probably needs to keep rising.
As much as higher interest rates and unemployment are painful, letting prices keep growing well above 2 to 3 per cent a year, is not fun for us, either — and could make it even harder and more painful to bring down later (think: more interest rate hikes and job losses).
The fact is that the Reserve Bank has two jobs itself: to keep inflation low and stable (at between 2 and 3 per cent), and to maintain full employment: the lowest level of unemployment that is consistent with keeping price pressures under control.
The first objective includes a hard and fast target — one which we know, for a fact, is not being met because inflation came in at 3.6 per cent in August.
The second objective: full employment, is more ambiguous because it requires figuring out exactly how much unemployment contributes to price pressures (something that is up for debate) — and therefore at what rate it should sit.
The Reserve Bank has previously said it believes the appropriate rate of unemployment to keep inflation stable is 4.5 per cent. But some economists, including University of Melbourne labour economics professor Jeff Borland, believe it could be lower — in Borland’s case, closer to 4 per cent.
Still, Borland believes it’s reasonable for the bank, right now, to be eyeing an unemployment rate above 4.5 per cent. Why? Because there are a bunch of supply shocks (such as war in the Middle East causing oil prices to surge) that we’re muddling our way through.
Raising interest rates doesn’t really do anything about supply shocks — or supply in general. And because price growth is largely determined by the balance between supply and demand, all the bank can do with its one superpower is influence demand.
Rather than parading around with various goods and services on an Instagram or TikTok video, the bank influences our spending habits by setting the country’s interest rates.
Changes to interest rates hit the economy in multiple ways, but the main way is by reducing or increasing the money that households with a home loan have left to spend on things. That shrinks the total level of “demand” in the economy, and businesses aren’t able to raise their prices as much because there are fewer customers willing or able to keep paying higher prices.
Because the bank can’t do anything about supply side issues, it has to double down by cracking down on demand. That is, mortgage payers in particular, need to be whacked a bit harder than they otherwise would if these supply shocks were not happening.
Doing this, of course, also affects people’s employment. Why? Because if Australians are spending less and slowing down the economy, businesses may look to pause hiring or cut back on the number of staff that work for them.
‘Still a bit too tight’
Higher unemployment is not, in and of itself, an objective anyone is aiming for. But the unemployment rate can be an indicator of how much pressure the economy is under. And an especially low unemployment rate can worsen inflation.
When the unemployment rate is low, meaning there are very few people (who are actively looking for a job) unable to find work, it means there’s only a relatively small pool of people businesses can look through when they’re filling a role.
When there aren’t many people available and wanting to work, businesses have a harder time finding the right people with the right skills for the job. And that might mean they have to offer higher salaries to attract and keep workers.
If this happens broadly across the economy, it can lead to overall wage growth.
That might seem good: who doesn’t love a pay rise? But because wages are one of the major costs businesses face, an increase in wages can lead to businesses passing on this cost through higher prices, which we know of as inflation.
It’s worth noting, of course, that this pass-through effect has weakened, especially as union membership has fallen: individual workers generally have less power to ask for higher wages than if they asked together as a bigger group.
The most recent data shows the unemployment rate in August was 4.6 per cent: up from about 3.5 per cent in 2022 and 2023, but relatively low by historical standards. It’s a level the bank still thinks is “still a bit too tight” (meaning a level that is still putting pressure on inflation).
But as Borland points out, “real unit labour cost” growth: a gauge of wage pressures accounting for inflation — and the wage measure that ultimately matters most for businesses when setting their prices — hasn’t been all that high. In the year to June, it climbed a relatively modest 0.5 per cent.
Arguably, that can still be inflationary, pushing up the wages businesses have to pay. But it’s an amount that could be absorbed by many businesses rather than being pushed through to higher prices.
The key in all of this, of course, is to improve productivity growth which, as Bullock has said, is currently “doing nothing”. If we’re able to find better ways of doing business (such as by using technology) that require fewer resources, or help us produce more – and better quality – things, we can have both higher wages and lower price growth.
While higher unemployment might be a sacrifice we have to make until our current supply shocks resolve, I’m less certain it’s a price we need to pay once they blow over.
The Business Briefing newsletter delivers major stories, exclusive coverage and expert opinion. Sign up to get it every weekday morning.
 Millie Muroi is the economics writer at The Sydney Morning Herald and The Age covering workplace and economics. She was formerly an economics correspondent based in Canberra’s Press Gallery and the banking writer based in Sydney.Connect via X or email.


