
Source : THE AGE NEWS
If the US Federal Reserve Board had met a day or two later, would it have left interest rates on hold?
In explaining why the Fed kept its policy rate, the federal funds rate, unchanged after this week’s meeting of its Open Market Committee (FOMC), the central bank said it needed more data. “The accumulation of more information will help the committee determine the policy stance appropriate to ensure a timely return of inflation to the committee’s 2 per cent goal,” it explained.
More information will become available within 24 hours of that statement, with the release of the Personal Consumption Expenditures (PCE) report for September on Thursday at 11.30pm AEDT, along with GDP data. The PCE price index is the Fed’s preferred measure of inflation.
It would be a surprise if that data doesn’t show US inflation continuing to accelerate, given the most recent consumer price index report for September showed a 0.6 per cent rise in the headline inflation rate, with price increases both gathering pace and broadening throughout the economy.
In the circumstances, a central bank committed to bringing inflation under control could have justified increasing its policy rate for the second time in this cycle. Indeed, two of the 12 voting members of the FOMC – Lisa Cook and Beth Hammack – voted for a 25 basis point increase.
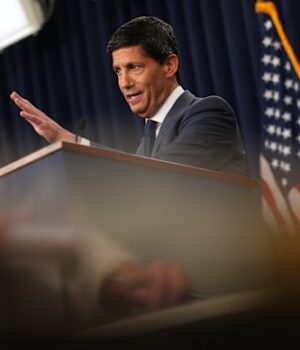
The Fed’s chairman Kevin Warsh was asked at the press conference after the meeting why, if inflation was high, the bank hadn’t raised rates. He didn’t provide a direct answer.
‘I just spent two days with my colleagues upstairs. I didn’t hear an utterance about politics… I didn’t hear anything about it and I don’t believe it had any role in the decision.’
Federal Reserve chair Kevin Warsh
“If the crux of your question is ‘you haven’t achieved price stability,’ you’re right,” he said, adding that the central bank was committed to achieving that stability.
He denied that next week’s midterm election influenced the decision to keep rates steady, saying “politics played no role.” President Donald Trump would have had a meltdown had the Fed raised rates days ahead of those elections.
“I just spent two days with my colleagues upstairs. I didn’t hear an utterance about politics. I didn’t hear a reference to politics, elections, what’s happening in the next week, or so. I didn’t hear anything about it and I don’t believe it had any role in the decision, not just for me, but my colleagues around the room,” Warsh said.
The Fed would have a better understanding of the economy and financial markets at its next meeting, as the “period right in front of us is information-rich,” he said.
The Fed chair conceded that inflation was too high and said he and his colleagues would “own” the Fed’s 2 per cent inflation target. America’s headline CPI inflation rate was 3.7 per cent last month, while “core” inflation (excluding volatile food and fuel prices) was 2.6 per cent.
“We’re taking responsibility for it, and if you think that we’re tolerating some inflation targets somewhere in the twos, let us disabuse you of it,” he said.
While the Fed might have hit pause after its first move in the rate cycle – the 25 basis point increase in the federal funds rate last month was the first rise in three years – it seems inevitable that there will be more. Financial markets are pricing in another 25 basis points in December, and at least two more rate hikes next year.
Trump’s inflation boosters
The inflation rate is being driven by Trump’s tariffs and his war in the Middle East, which has seen oil prices trading well above $US100 a barrel – Brent crude costs more than $US114 a barrel – which, in turn, has caused price spikes in the prices of gasoline and diesel.
The increased cost of diesel, in particular, will steadily feed into transport and agricultural production costs, and then into consumer prices and inflation.
While it has taken time, Trump’s on-again, off-again, on-again tariffs are also starting to show in the most recent economic data, with the cost of basic consumer goods rising.
Add in the impact of the extraordinary investments in artificial intelligence, which are driving the costs of chips and computing power, electricity, water, commodities and construction materials, and there’s an inflation tide running through the economy.
AI is helping to grow the US economy, with Warsh saying it was likely the GDP numbers this week would show annualised growth of more than 3 per cent in the September quarter.
The Fed’s summation of the state of the world’s largest economy was that it was expanding at a strong pace, even as uncertainty remained elevated due to “geopolitical developments.” (There were no explicit references to the war in the Middle East).
Domestic spending was holding up, productivity growth was strong and capital investment robust. The unemployment rate was stable.
Warsh said the AI boom was playing a role in driving inflation and growth and was an important factor in the strength of the economy, but not the only one.
He argued, as he has previously, that productivity growth was picking up, allowing the US economy to grow faster without inflation – even though there has been modest improvement in productivity, while there’s plenty of evidence to show the AI investment boom is contributing to the acceleration in the inflation rate.
The Fed may be hoping financial markets will do some of the heavy lifting in bringing inflation under control.
While bond yields have eased a little from earlier this month, when they reached their highest levels in more than two decades, they remain high and are tightening financial conditions for companies (including the increasingly cashflow-negative AI companies, which are issuing more bonds to fund their massive spending) and households.
While Warsh was unwilling to label economic conditions “tight,” he did say they were tighter, with market participants becoming “more discerning in their capital allocations.”
Midterm crisis
Higher bond yields are a direct threat to the stability of some of the more overly-leveraged AI infrastructure providers.
They’re also an issue for the US government as they increase the interest costs of its $US40 trillion-plus debt and raise questions over the sustainability of a deficit running above 6 per cent of America’s GDP.
That’s why Trump and his economics team are so fixated with the Fed, with the president continually haranguing the central bank for not cutting rates dramatically.


