
Source : Perth Now news
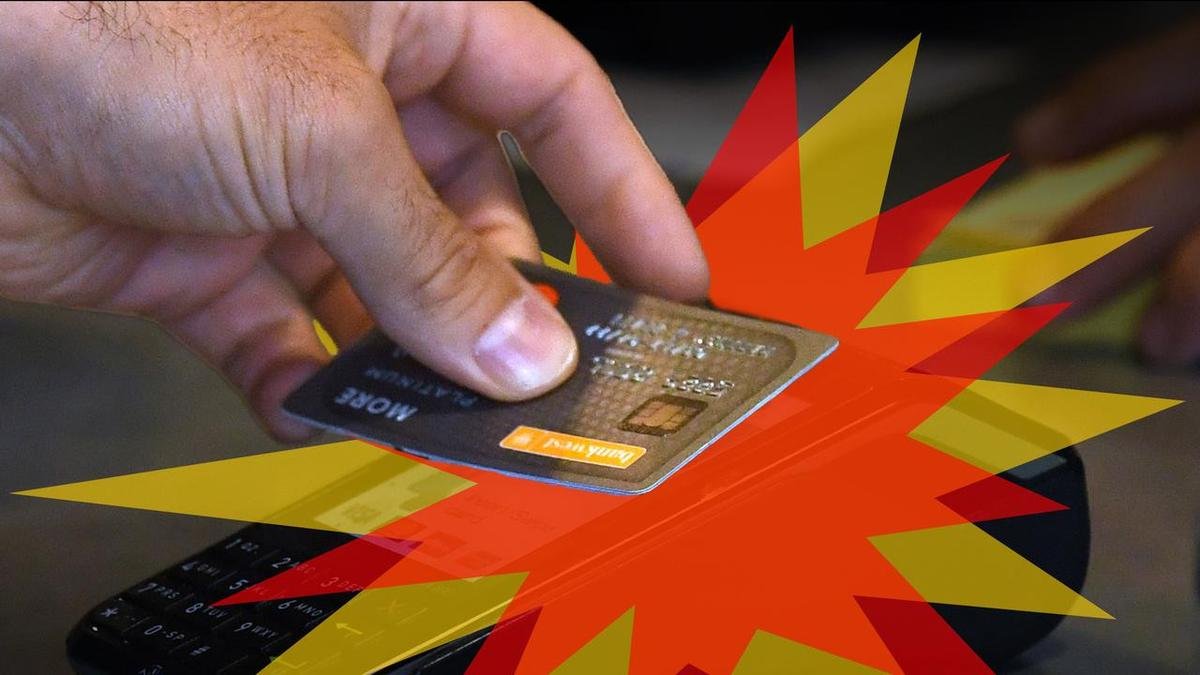
A ban on card surcharges is supposed to deliver savings for Australian shoppers, but the reality could be quite different if retailers raise prices and the banks claw back losses by axing rewards.
The reform, driven by the Reserve Bank of Australia, comes into effect from Thursday, when anyone paying with a debit or credit card will be spared the surprise of extra charges at the till.
Under the new rules, retailers must either absorb the cost or build it into their prices.
But they could also offer a discount for cash or payment services such as PayID, which some experts think could lead to savings of up to 10 per cent off the transaction price.
Cash fan Steve Worthington says it can’t come soon enough, after the Australian Consumer and Competition Commission earlier in September confirmed it would be legal for businesses to discount against their displayed prices.
“I suspect a number of merchants will start to do that, to offer a discount for cash,” the Swinburne University of Technology professor and payments system expert told AAP.
However, dealing in cash means keeping a float and taking it to the bank at the end of the day, which can be difficult given the general decline in branches across the country, and does lay a burden on small business owners.
“But nevertheless, I think a 10 per cent discount might be an attractive basis for people in this era of the cost of living,” said Professor Worthington, who thinks discounting could fuel cash use.
Cash makes up barely 15 per cent of all counter purchases, against a spike in card use – debit, credit or charge – to 73 per cent, according to the latest central bank data.
“I pay already in cash for certain places because I just don’t like being surcharged because it’s just really pathetic,” Prof Worthington said.
For those sticking to tap and go, there’s a good chance some businesses will raise prices to offset the merchant fees they still pay to the banks and payment providers to process those payments, which they used to recoup under surcharges.
According to the central bank’s inquiry into surcharges, about 80 per cent of businesses absorbed the cost but smaller enterprises, such as cafes and restaurants, passed it on.
This is where the RBA’s decision to cut interchange fees – the fee paid by the merchant’s bank to the customer’s bank each time a payment is processed – could come into play.
The new maximum rate will be 0.30 per cent – or about three cents on a $10 spend – down from 0.80 per cent, and has been set to compensate payment providers, like banks, for the ban.
“The biggest issue for those small businesses is whether they actually receive the benefit of the interchange cuts,” RMIT University’s professor of finance Angel Zhong said.
“My advice is to call your payment provider now and ask if you can get a better deal.”
Down the track, retailers will have better visibility on their merchant fees because the RBA plans to publish pricing information from card networks, making it easier to find a better deal.
The surcharge ban is tipped to deliver more than $1 billion in savings for consumers, the RBA believes, but like all things in life, someone has to pay.
And while market watchers are waiting to see how retailers and consumers react, one thing seems likely – it won’t be the banks.
The banks are already trimming lucrative credit card reward programs and hiking annual card fees, because payment processing doesn’t happen for free.
“Banks – payment providers – they need to make revenue. They’re not running a charity,” Prof Zhong said.
“A cake is only so big, so if you’re making one slice smaller or bigger, then you need to change the size of the other slice.”