
Source : Perth Now news
Australian consumers could soon be paying less for everyday items as a “plot twist” emerges with the card surcharge ban.
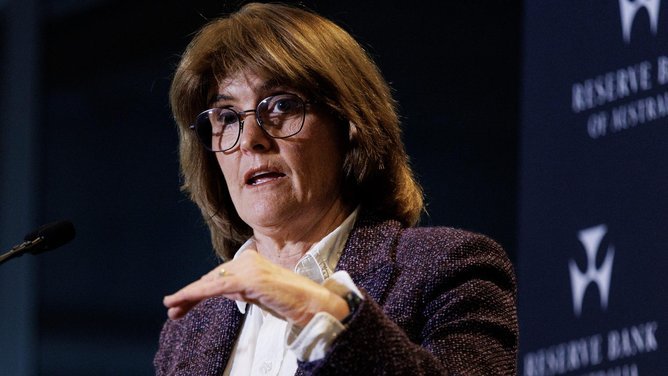
Sold as a huge win for households, the Reserve Bank ended pesky surcharges placed on the end of purchases starting from October 1.
This is supposed to save households $1.6bn a year, although sceptics claim businesses will just increase the sticker price and actually cost households more.
But in a bizarre twist, Cash Welcome founder Jason Bryce told NewsWire physical tender would become more appealing to consumers as businesses could offer a discount for cash usage.
“This is big news and the Reserve Bank cannot be more explicit, a business can take off their card surcharge time and replace it with a cash discount sign,” he said.
“It is a bit of a plot twist because a cash discount or a card surcharge it is almost equivalent in a way, just the other side of the coin.”
As part of the Reserve Bank’s changes to card payments, businesses must display the entire cost of a product or service as the sticker price, including any transaction costs associated with card payments.
However, businesses will now be able to offer discounts for cash payments, below this sticker charge, if they decide not to pass on the surcharge cost to cash users.
This means the price could theoretically be below the sticker price.
Under its own frequently asked question section, the Reserve Bank confirms businesses can offer discounts for forms of payments that are not card transactions.
“Businesses that wish to steer consumers towards other payment methods can do so by providing discounts instead of using surcharges,” the RBA said.
Meanwhile the ACCC said businesses could offer discounts for payment methods such as cash or PayID.
“Payment method discounts should be clearly disclosed before consumers choose to book, order or pay,” their website stated.
“The price of any item that is displayed to consumers must be the full price they will pay if they do not receive the payment method discount.”

Mr Bryce forecasted more retailers would start offering cash discounts due to it becoming cost competitive compared with card payments.
“I expect a lot of retailers to go cash only from October 1,” he said.
“Surcharge fees are inescapable, businesses get a bill at the end of the month and the only way to not pay that bill is to not accept card payments.”
What is changing?
Paying those extra couple of cents when tapping your card to pay for a cup of coffee or the morning newspaper could soon be a thing of the past, thanks to a major change to the card system.
Starting from October 1, businesses will be banned from surcharges on card transactions and instead will be forced to put the full price on the label.

This is expected to save households $1.6bn directly in surcharge payments, although sceptics point out businesses will simply lift prices to compensate for higher fees.
The major changes were first announced on March 29 by the Reserve Bank of Australia, but gave businesses six months to comply with the new plan.
As part of three key changes, the RBA said it was removing surcharging on debit, prepaid and credit cards across eftpos, MasterCard and Visa networks.
Instead, businesses would be required to include the entire price – including any costs to issue credit – as part of the sticker price.
Australians are slugged about $1.6bn in surcharge payments every year, while businesses pay $200m to card providers.
To compensate businesses, the changes also include the “interchange cap” will be dropped from 0.8 to 0.3 per cent for domestic-issued consumer credit card transactions.
The RBA estimates this will save businesses $910m.
The introduction of an interchange cap on foreign cards will start six months later on April 1, 2027.
NED-9108-Monthly-Inflation-Indicator
Businesses warn it will smash tight margins
Despite being labelled a win for consumers, business advocate groups warned it would simply lead to higher prices and worsening margins.
Independent Payment Forum co-founder Brad Kelly told NewsWire it would ultimately hurt the Australian economy.
“Reforms are not fit for purpose and will lead to significant price hikes for consumers and bill shock for small businesses when they can least afford it,” he said.
“Of course merchants will turn to cash as an alternative. We will see a lot more ATM’s in businesses in Australia.”

Mr Kelly warned the RBA and ACC would wash their hands if any consumers noticed surcharges, simply leaving it to businesses to clean up any messes.
“As we start to close out the last part of 2026 the payments utopia that was promised with low fees to merchants and a surcharge free merchant experience may descend into a chaotic mess that could take years to recover from,” he said.
The Council of Small Business Organisations Australia chair Matthew Addison previously warned any changes made to card payments would just hurt already struggling small businesses.
“If you ban surcharging without guaranteeing lower fees, small businesses have no choice but to absorb the cost and that will ultimately be reflected in prices,” he said.
Mr Addison said small businesses did not control how customers chose to pay, but they did carry the cost of those payment methods.
“Surcharging has been one of the only ways small businesses can recover these costs,” he said.
“If you remove that without fixing the underlying fees, you’re asking small businesses to wear them.”